So far, the biggest winners of the AI boom have been the companies building its foundations, especially the chip makers.
Software and services firms, by contrast, were widely seen as AI’s structural losers. The fear was that inexpensive AI agents could do the work of the costly, complex software sold by large companies. The market called it the “SaaSpocalypse.” Software shares fell 50% or more, and valuations dropped to near-record lows.
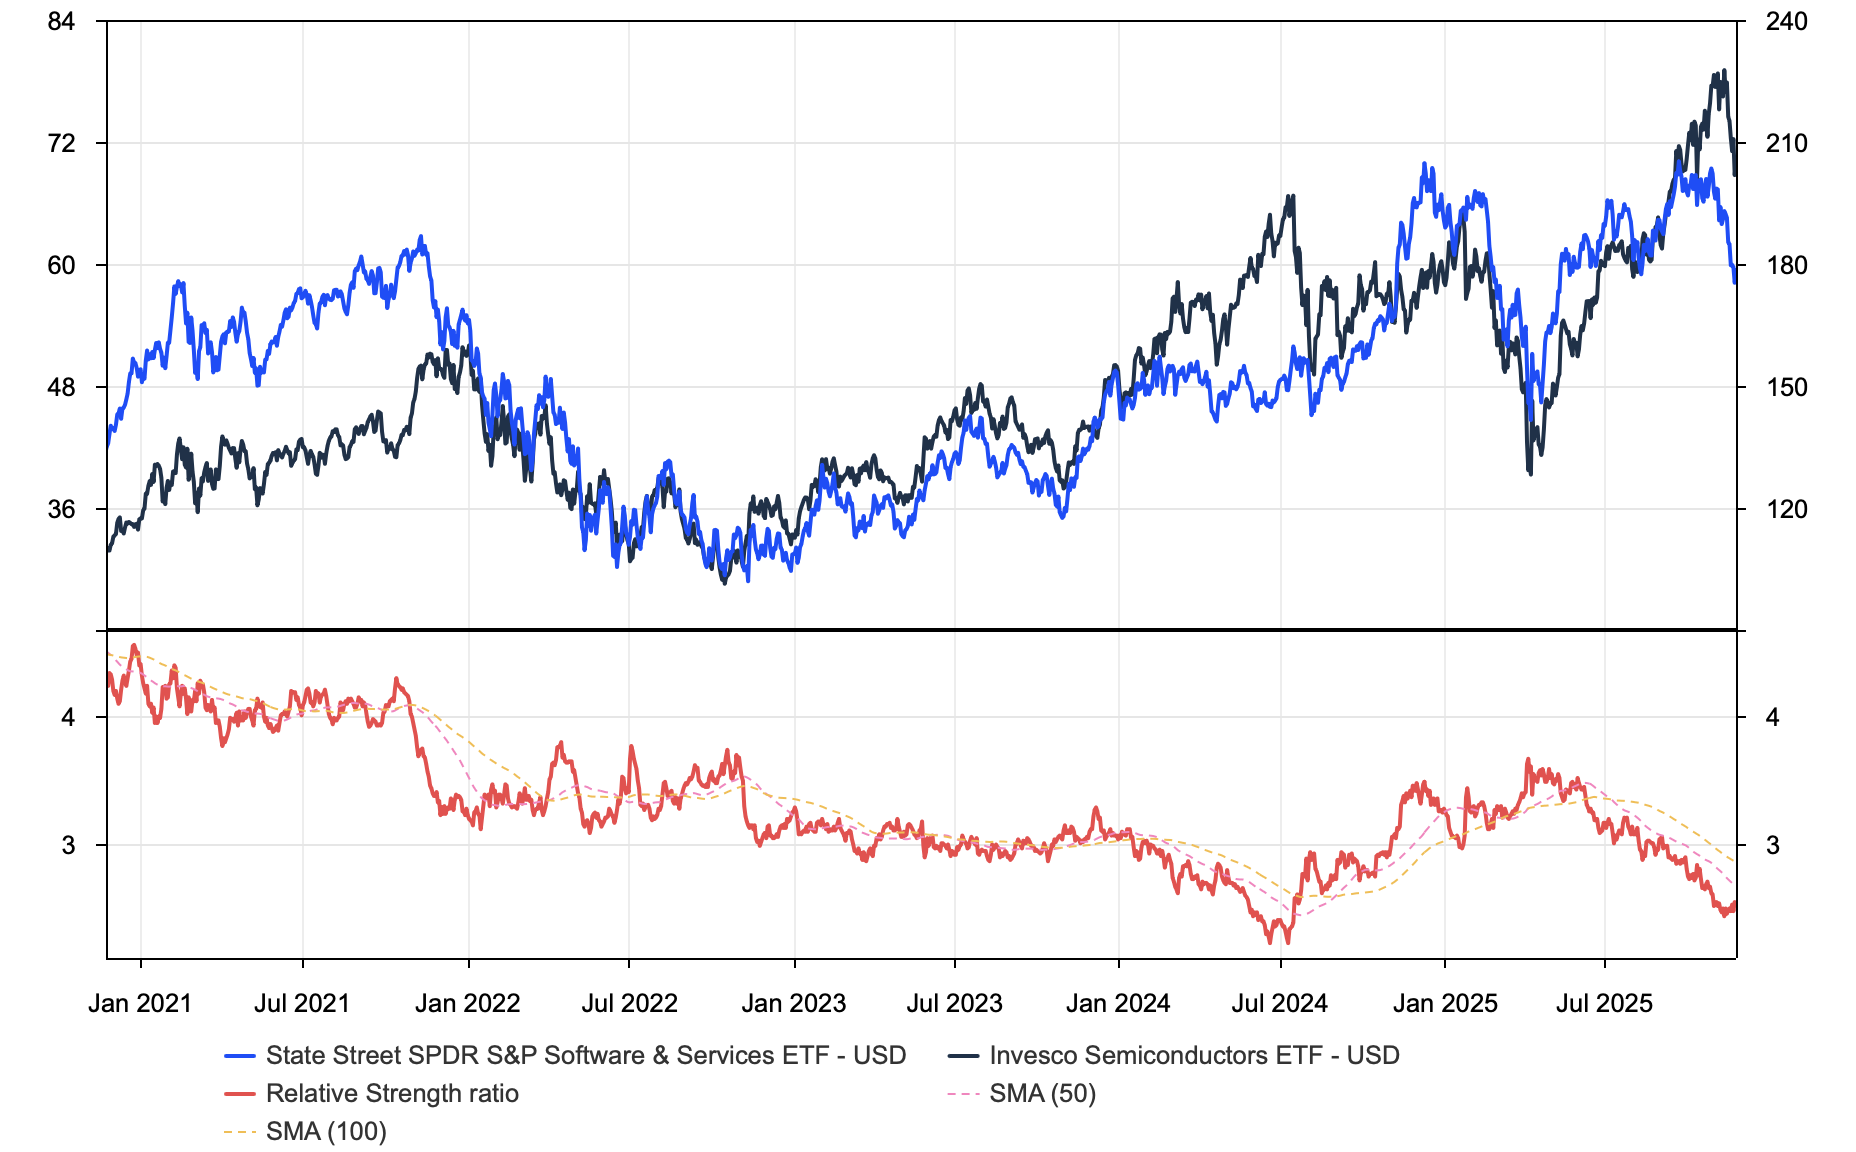
Over the past five years, the Invesco Semiconductors ETF (PSI) has gained 260%, while the State Street SPDR S&P Software & Services ETF (XSW) has risen just 15%.
Software shares fell 50% or more, and valuations dropped to near-record lows.
Accenture’s shares, on the other hand, jumped 16% after it confirmed modest expected revenue growth of 6% in 2027.
The gap is stark. Over the past five years, the Invesco Semiconductors ETF (PSI) has gained 260%, while the State Street SPDR S&P Software & Services ETF (XSW) has risen just 15%. Even the iShares Expanded Technology-Software Sector ETF (IGV), with its larger, more growth-oriented companies, is up only 35%.
Signs of a turn
But there are signs the gap may be starting to close. Lately, strong results from chip makers have been met with selling, while software results have sparked sharp rallies. Micron Technology’s shares failed to rise after it reported record profits. Accenture’s shares, on the other hand, jumped 16% after it confirmed modest expected revenue growth of 6% in 2027.
As the chart below shows, software and technology services shares have held their 2024 lows relative to semiconductor stocks (the red line), and are turning up. If this trend persists, and fundamentals, valuations and momentum are all supportive, the reversal in performance could be powerful.
Positioned for the shift
Both software ETFs, XSW and IGV, are well positioned to benefit from this shift within tech. XSW adds more exposure to value and small-cap companies, which makes it the more diversified of the two.
Views are the author’s as of October 1, 2026 and are not investment advice.