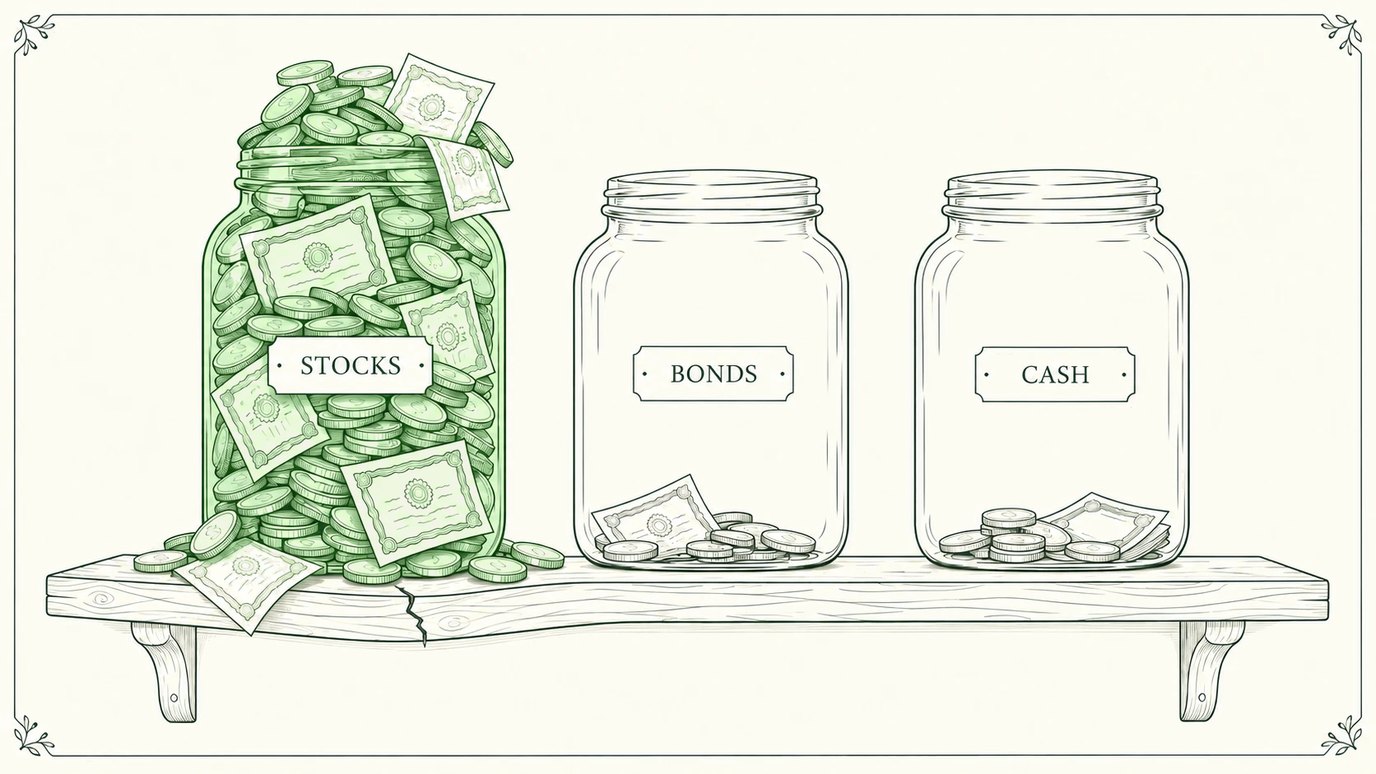
There are times when a chart, a headline or a single thought cuts through all of the noise. Something so profoundly clear and important that it takes a moment to fully process.
I was searching for an update on the AIAE, the aggregate investor allocation to equities. It measures investors’ exposure to stocks as a percentage of their total assets. First published by Jesse Livermore and later tested by Raymond Micaletti in Towards a Better Fed Model, it has proven to be the best indicator of forward 10-year average annualized equity returns. Better than the more popular Shiller CAPE ratio. Better than the Federal Reserve model.
The math is brutally simple.
The math, and the investor behavior that drives this model, are brutally simple. They were part of the foundational observations that led me to create Flextion.
The AIAE shows a strong inverse relationship between investors’ exposure to equities and the returns they actually go on to realize. The correlation is nearly 80%.
We are in the 100th percentile of this indicator going back to 1945.
The correlation is nearly 80%.
In 2000, the model projected a -3.3% return. The actual result was -2.6%.
That downward slope is due to the negative second derivative of investors’ generally poor timing decisions. It shows that most money enters near a short-term performance peak, and then mean reversion drives down actual returns.
Off the charts
Given my understanding of this relationship, the following chart, found at historyofmarket.com, is striking.
We are in the 100th percentile of this indicator going back to 1945. The resulting forecast for the next decade, expressed as an equity return relative to 10-year Treasuries, is negative 800 basis points.
Right at the extremes
I went back and looked at the two previous extremes since 1945. Both times, the model was correct in forecasting a low or negative return decade.
In 2000, the model projected a -3.3% return. The actual result was -2.6%. In 1968, in the Nifty Fifty bubble, the model projected +0.8%. The actual result was -1.04%.
So the indicator has been historically accurate at the extremes.
This is not meant to be a precise short-term timing tool. The next five years could be much better, and the following five years much worse. But the current reading points to the importance of preparing for the increasing odds of low returns over the coming decade.
Preparing for a low-return decade
At Flextion, we are focused on helping advisors mitigate the impact of an extended low-return environment, with managers poised to outperform and exposed to diversifying factors such as dividends, quality, value, small caps, international, real assets and defensiveness.
Good timing of decisions is always important. It may be especially critical if the best predictor of long-term returns is right. Flextion is here to help.
Views are the author’s as of October 13, 2026 and are not investment advice.